As local banks vanish, foundations should fill the lending gap
Grants alone can't build affordable housing, train workers, or revive rural economies. Mission-aligned lending can extend philanthropy's reach.
By Antony Bugg-Levine
Contributor
August 4, 2026 | Read Time: 6 minutes
Benjamin Franklin knew what a difference a loan could make. When he was a young man, two friends in Philadelphia lent him money to start his own print shop after he fled indentured servitude in Boston. He later described that loan as “the foundation of my fortune and all the utility in life that may be ascribed to me.”
So, to pay it forward, he amended his will in 1789 to set up loan funds in Boston and Philadelphia for young tradesmen to start their own businesses. Workers would borrow for up to 10 years at 5 percent annual interest with repayments ploughed back into future loans. Fascinated by the power of compound interest, he stipulated these funds to run for 200 years, with the balance to be donated to the cities. Already a pioneer of American philanthropic innovation as the inventor of the matching grant concept, Franklin created another long-lasting idea: a philanthropic endowment and a sunsetting foundation.
Almost 200 years later, the trustees of the Blandin Foundation in Grand Rapids, Minn., at the headwaters of the Mississippi River, realized that fulfilling their mission required running a similar play. The foundation was founded in 1941 by Charles K. Blandin, owner of the Blandin Paper Company, the region’s largest employer for many years. As the paper mill started shedding jobs in the 1980s, the foundation trustees realized that living up to their mandate — promoting the beauty and economic vitality of the Grand Rapids area — would require supporting local small businesses that could create new jobs. So they started making loans in 1987 to small businesses.
Now they work closely with regional development authorities and others to identify where small loans can make a big difference, recycling the money back into new investments when they are repaid.
What unites these stories — 200 years and 1,000 miles apart — is the simple recognition that extending who gets access to an affordable investment is a powerful way to help our country realize one of its founding ideals: that hard work can lead to security and prosperity. Because foundations, philanthropists, and nonprofits can make investments that serve their mission, they have the ability to expand financial access where mainstream investors won’t go.
Extending affordable financing alone will not be enough to solve our major national challenges. But it’s hard to see how we will build more affordable housing, expand training and education to all the people who need it, navigate technology-induced economic shocks, protect our climate and natural heritage for future generations, and solve other national priorities unless more people and organizations can access the investment capital they need to turn opportunity and hard work into progress.
Too Few Banks
As Franklin and the Blandin Foundation trustees recognized: We cannot wait for commercial lenders to do this on their own. The number of banks in the United States has shrunk 75 percent since the mid-1980s, leaving especially rural areas without local lenders who can tailor loans to local opportunity. Venture capital and private equity investors continue to invest in a narrow set of businesses led by people from a narrow set of backgrounds.
Fortunately, foundations and nonprofits are stepping in to the gap, motivated by the recognition that expanding access to finance is crucial to meet their mission objectives. And, as the example of the Blandin Foundation shows, it’s not just large foundations with large investment teams located on either coast:
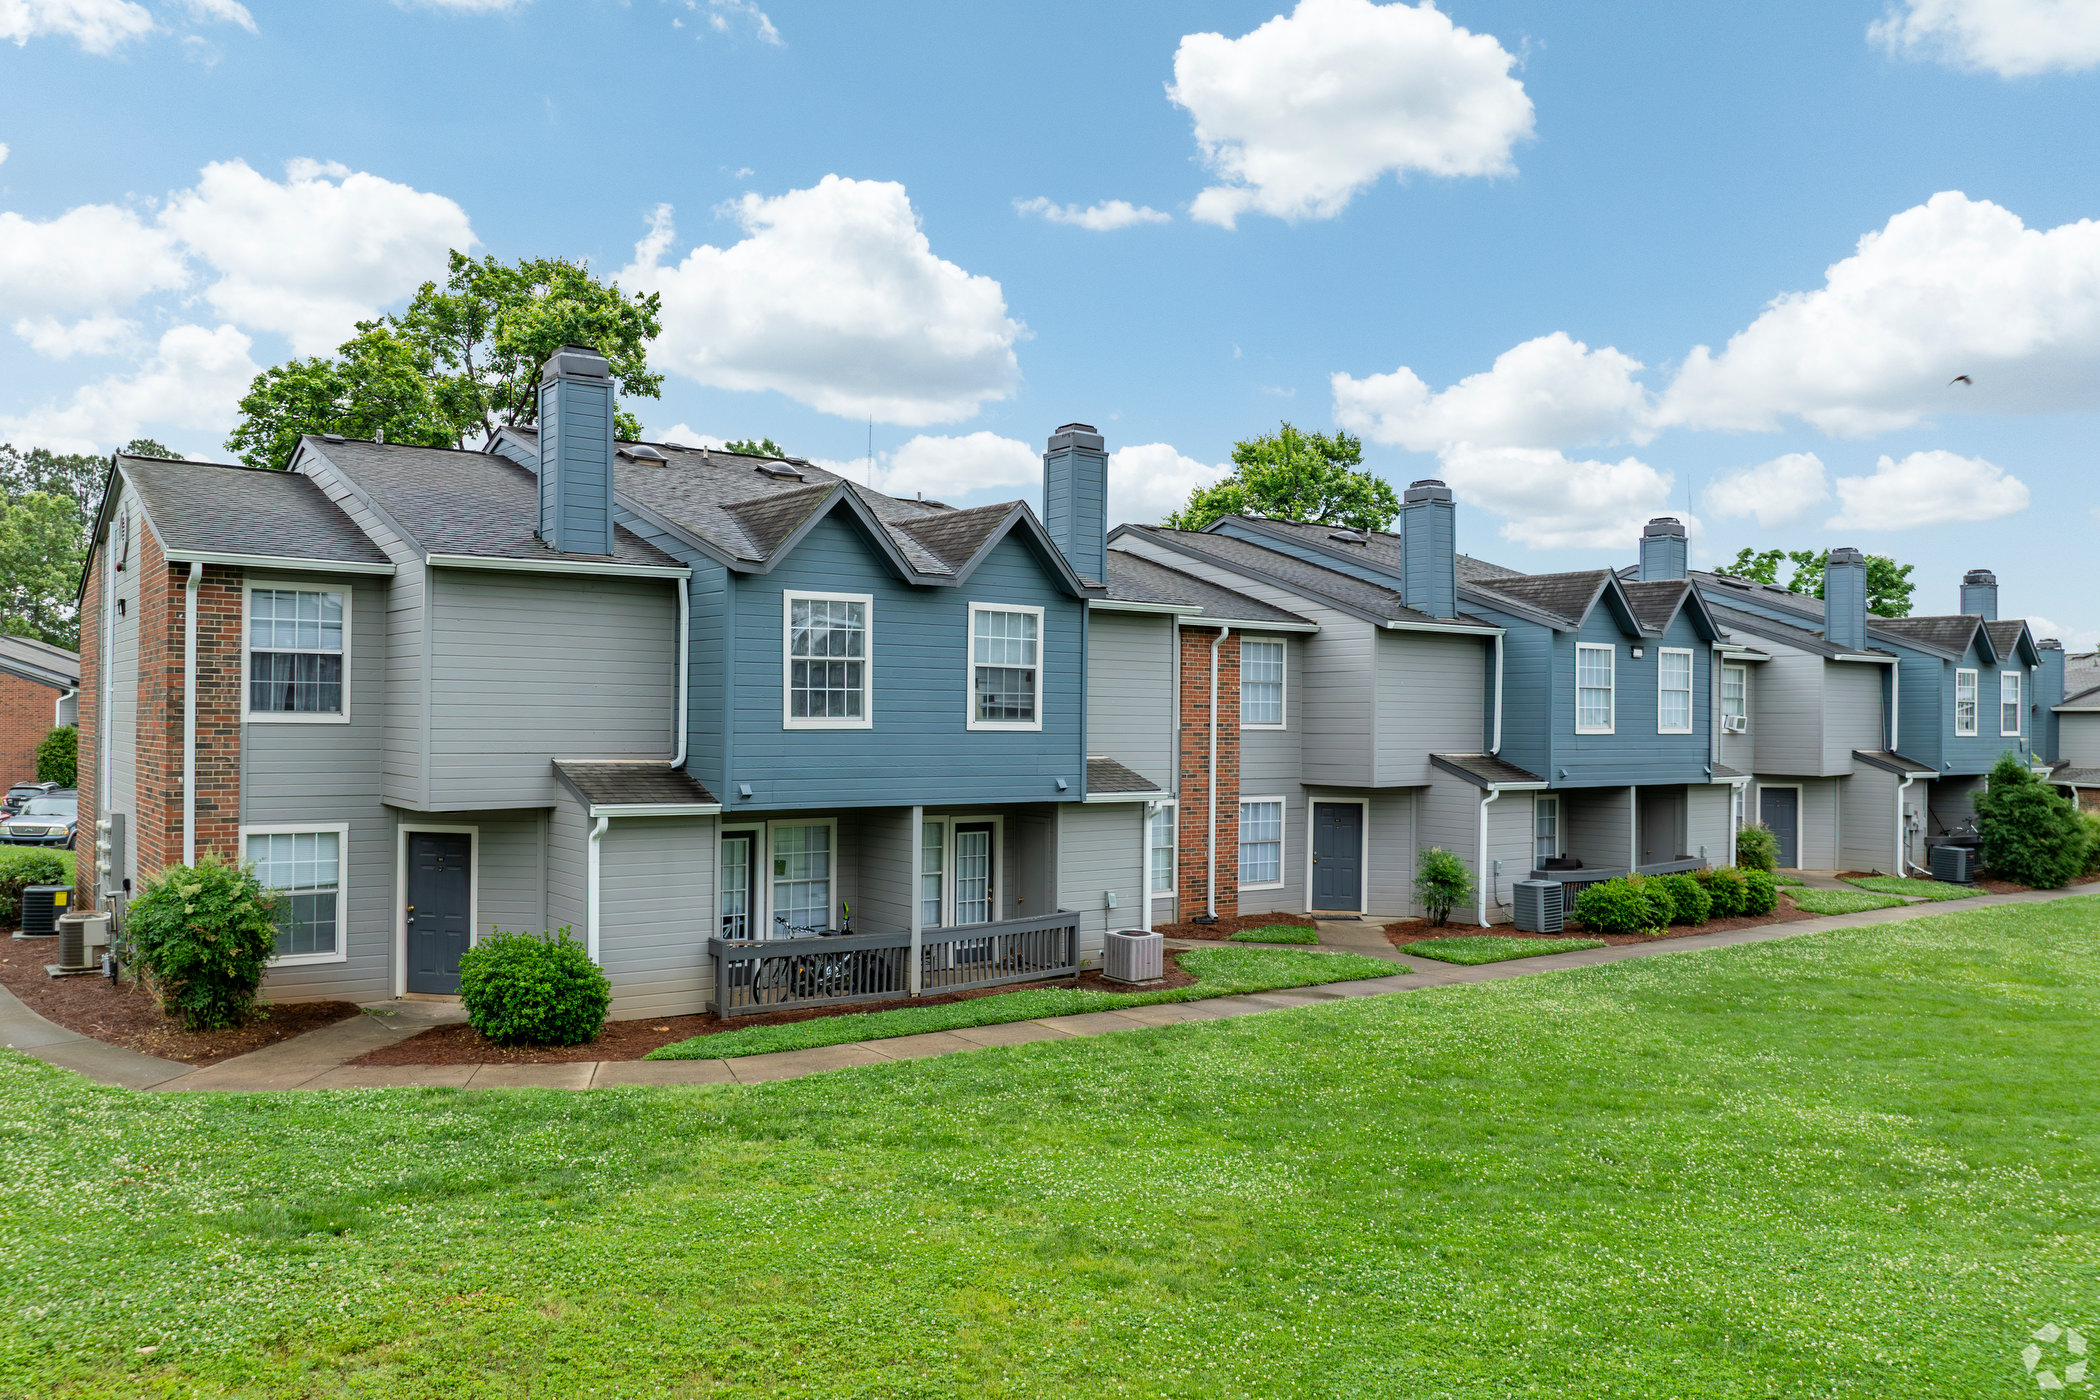
- The Leon Levine Foundation is investing through Ascent Housing and its affiliated funds — the Housing Impact Fund and the Charleston Workforce Housing Fund — to expand affordable housing development in Charlotte, N.C., and Charleston, S.C. It is also working through the BDP Community Solutions housing fund to create permanent homes for military veterans and others exiting homelessness.
- The Woodcock Foundation, a small family foundation, has made grants for years to support more environmentally friendly agricultural practices. To complement this work, it invested in Mad Capital, a Denver-based fund that provides loans to farmers to cover the costs of transitioning to organic production. Local banks won’t do that, even with the support of the $500 billion federal rural lending program.
- The Lumina Foundation in Indiana spent a decade in the early 2000s making grants to increase the number of Americans who could earn a post-secondary credential. When it recognized that start-up companies would also need to grow to meet their mission targets, it launched Lumina Impact Ventures in 2015 to invest in for-profit companies advancing equitable postsecondary education.
These are just a few of the dozens of examples of foundations, nonprofits, companies, individuals, and government agencies I learned about while researching my new book, Investing in America. They are Republicans and Democrats from all walks of life working in all parts of America. They are motivated not by ideology but by an honest assessment of what it will take to get results and a willingness to work with people they don’t always agree with in areas where they can find common ground.
How to Get Results
Investing in America is not a spectator sport. You or your organization can deposit your cash with a community bank that makes small business and mortgage loans available to people left out by the risk assessment algorithms of the big banks. Like the Blandin Foundation, any grant maker can work with local partners to identify lending needs in the communities where they work. And for philanthropies whose endowments already invest in private equity or venture capital, they can choose fund managers whose investments also support the foundation’s mission.
The rules governing foundations have long supported investing focused on serving the mission. Over the past 20 years, private and corporate foundations and nonprofits have shown many ways philanthropic assets can be used to make and spur investments that expand access to opportunity. And multiple bipartisan bills are advancing in Congress and various state houses that will make it easier, less risky, and more lucrative for investors who seek to harness private capital to solve national priorities, such as building affordable housing, expanding employee ownership, and producing more domestic energy.
Uncovering the stories I tell in my book has left me feeling optimistic and patriotic. Optimistic because so many committed, creative people doing so much powerful work will surely make meaningful progress together. And patriotic because this work sits on the foundation of the 250-year-old effort to help America live up to our founding ideals.
Investing in America is a vote of confidence in the people and places around us and a belief that we can create an economy that shares prosperity more broadly. America has built one of the most dynamic economies in the world. It’s time we harness the full power of our vast investments, including the more than $8 trillion our foundations and nonprofits control, to renew faith in an American Dream that works for everyone.