Why Some Foundations Are Lending, Not Just Giving
Amid ongoing economic uncertainty, some foundations are pairing grants with loans and investments to help nonprofits build lasting financial stability, not just cover this year's budget.
By Stephanie Beasley
Senior Writer and Fellowship Director
July 24, 2026 | Read Time: 6 minutes
Cooperative Energy Futures, a member-owned clean energy cooperative in Minnesota helps low-income residents and communities of color access clean energy. The cooperative depends heavily on federal clean energy tax credits that are now being scaled back. And so philanthropic support has become more important, Timothy DenHerder-Thomas, the cooperative’s general manager said. And, he says, an unusual type of funding it receives from the Bush Foundation has been particularly helpful.
The foundation, a regional funder working across Minnesota, North Dakota, South Dakota, and 23 Native nations, provided the cooperative with a combination of a $2.5 million investment and a nearly $1.6 million grant. The investment from Bush funds the cooperative itself, including hiring staff, building data systems, and covering the early costs a project needs before it can even qualify for a bank loan, said DenHerder-Thomas. The organization, which is not a nonprofit, relies on commercial financing to fund individual solar projects, which gives it many sources of revenue.
“Capital from social impact investors is catalytic in getting those new projects off the ground,” DenHerder-Thomas said.
Once a project clears that early stage, the cooperative can turn to commercial banks to finance construction because they are better equipped to assess collateral risk against the solar equipment, he said.
The Bush Foundation has leaned into nongrant funding as another specialized way it can help the groups it supports beyond simply making grants. It has a $70 million portfolio of below-market loans and other investments, plus a small number of equity stakes, said Chris Romano, its chief operating officer. A separate pool of roughly $200 million sitting inside its endowment is used to make impact investments expected to earn a market-rate return while still advancing the foundation’s goals around climate, equity and regional investment, he said.
That kind of support isn’t right for every organization because it usually has to be repaid, or in the case of equity, the lender gets a stake in the organization, Romano cautioned. It tends to work best for nonprofits that generate their own revenue. And when a loan does make sense, Bush frequently pairs it with a grant rather than offering financing alone, he said.
“Some of it has been responsive to community need and community demand and what organizations are asking for,” said Ramla Bile, grant-making director for the Bush Foundation
More donors are starting to express interest in providing capital investments, such as low-interest loans and other types of nontraditional financing to help cover budget gaps that a typical grant isn’t designed to fill, said Joanne Sonenshine, a philanthropic adviser who helps funders develop new grant-making strategies.
Sonenshine, who worked with global funders on the Foreign Aid Bridge Fund — created to help international aid groups after the U.S. Agency for International Development was dismantled last year — said she hopes more foundation leaders will start approaching philanthropy with an investor’s mindset.
“I think we’re going to start seeing this year more donors trying things and saying, ’We’re testing this out even if we’re not sure if this will be the mechanism we’ll use,’” she said.
Nongrant Capital Can Bridge Hard Times
Capital investments are typically less about funding new programs than about basic financial survival, said Sam Marks, CEO of FJC, a 30-year-old public charity founded by philanthropists using donor-advised funds. FJC offers loans and other investment tools alongside traditional grants. Nonprofits often come to FJC seeking to smooth out cash flow disrupted by delayed government payments or other financial crunches. Many can’t get an affordable line of credit from a traditional bank, Marks said.
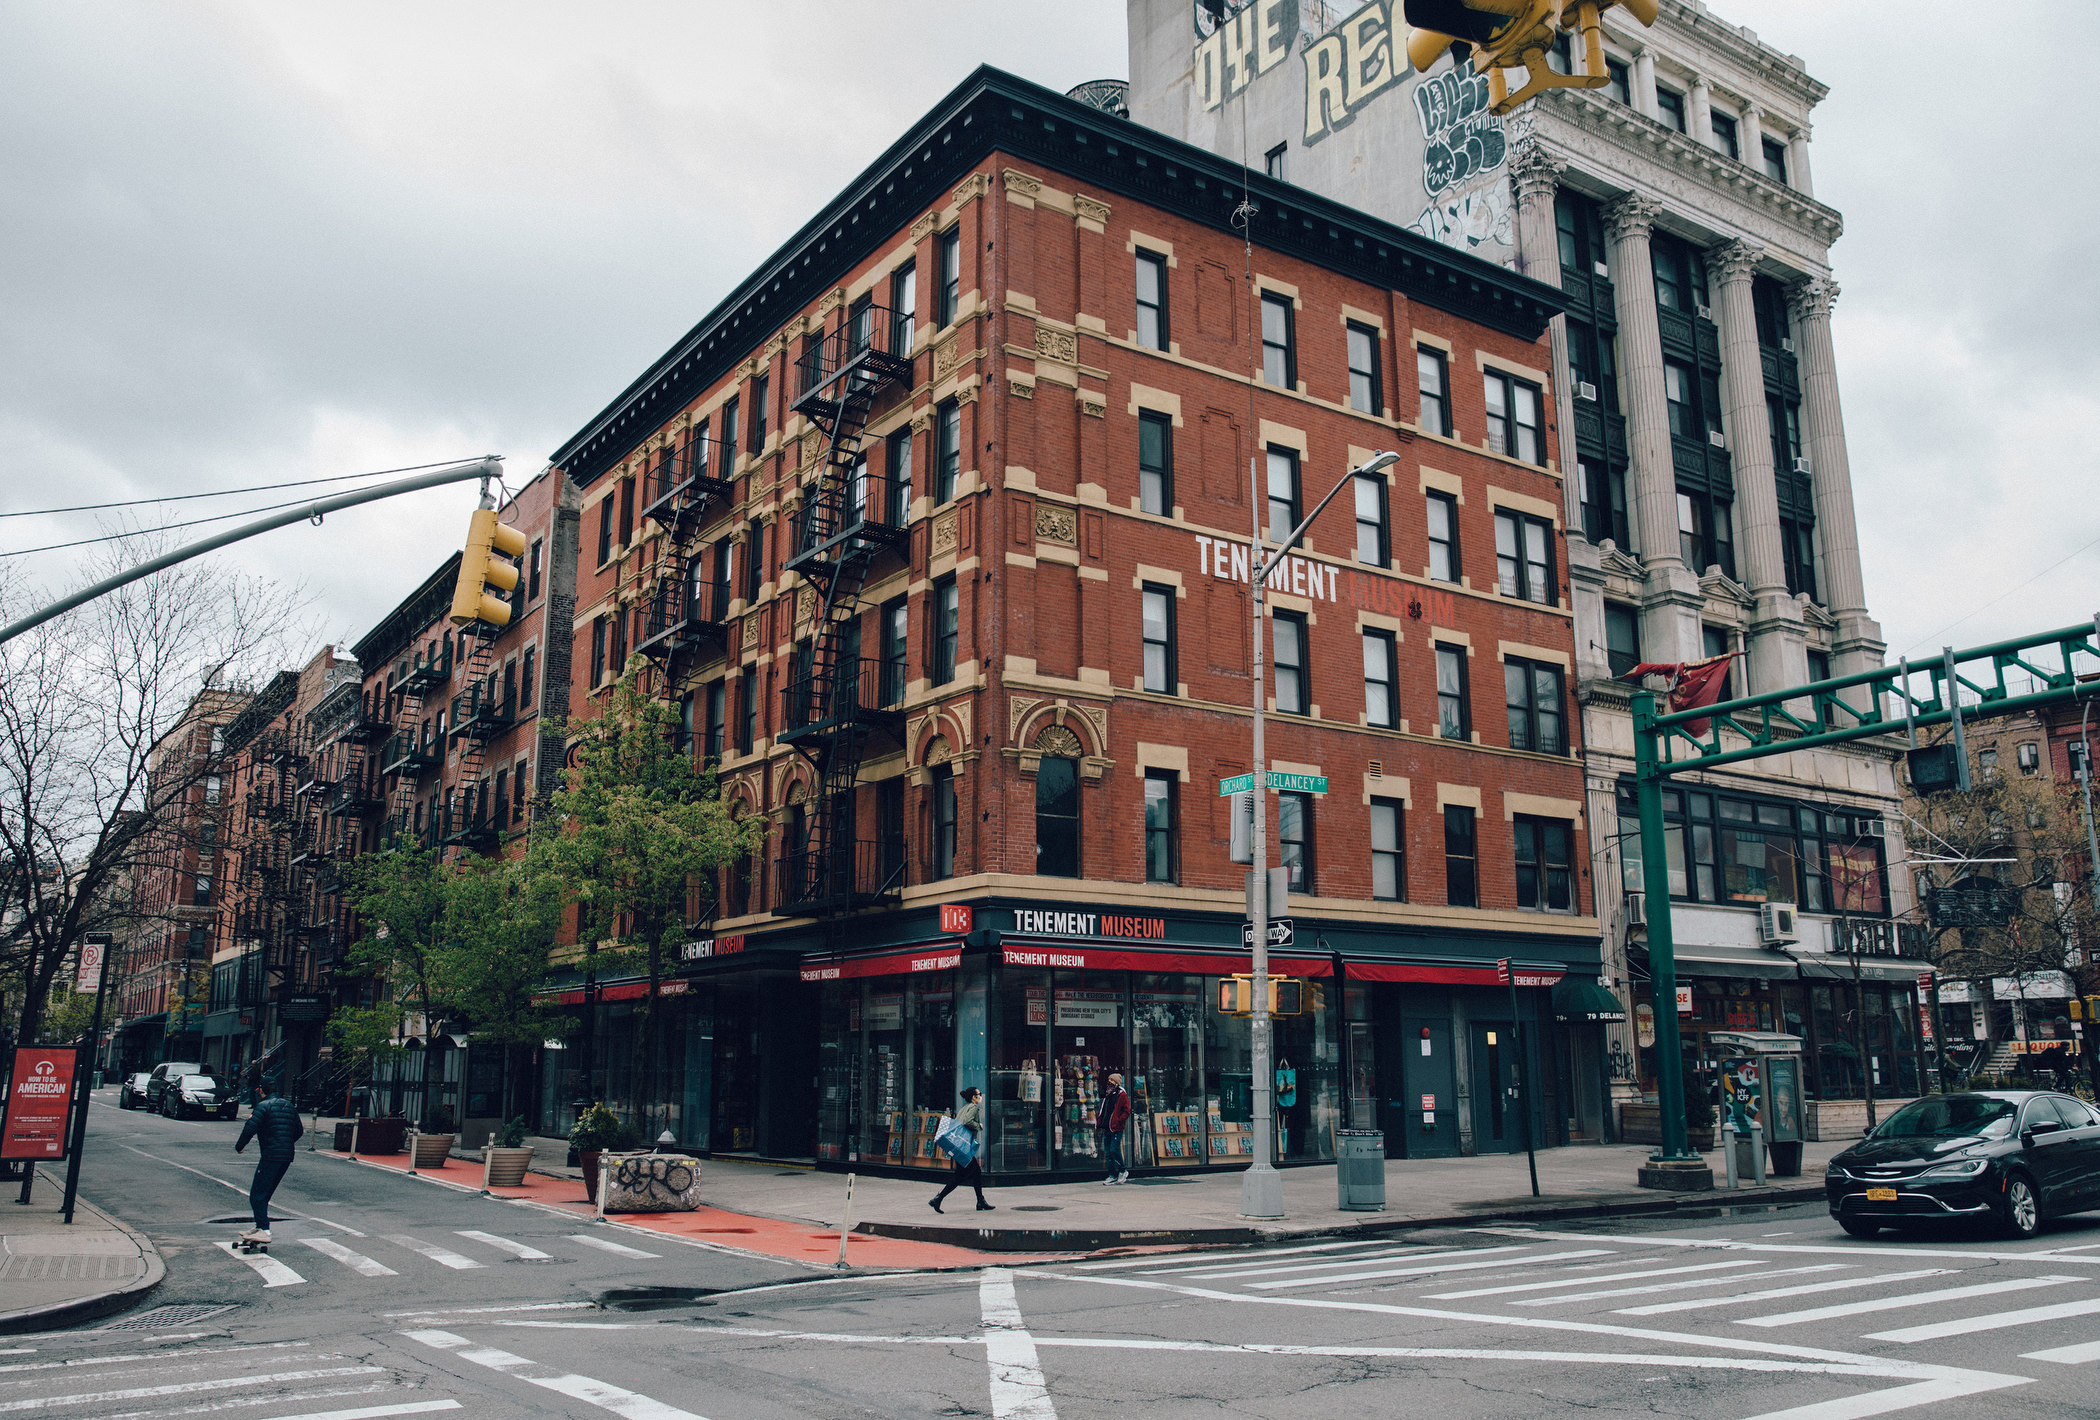
New York’s Tenement Museum is one example of how far that kind of capital can go. When it lost most of its revenue during the pandemic, the museum faced an existential problem. Admissions made up roughly 75 percent of its budget, yet it still had to make monthly $50,000 mortgage payments. A museum supporter asked FJC for help. FJC bought the tax-exempt bond behind the museum’s mortgage and rewrote the terms of the mortgage, bringing the interest down to 1 percent with no principal due for five years, saving the museum $2.5 million in debt payments.
“That’s the kind of use of philanthropic capital that can fundamentally change the organization’s balance sheet and help them through,” Marks said.
Just how many foundations and donors currently offer this kind of capital is hard to pin down. The IRS doesn’t track it closely and on tax filings, these investments mostly get lumped under the umbrella term “program-related investments,” said Brian Mittendorf, an accounting professor at Ohio State University who studies nonprofits. That catch-all category covers everything from low-interest loans to loan guarantees to equity stakes, which is all capital that, once repaid, can be recycled and reused for other charitable purposes.
Despite the advantages of this approach, many foundations hesitate to step outside of the world of traditional grant making. Sonenshine recently collected data on 381 philanthropic organizations. Only 115 of them used nongrant capital. That activity was among a diversity of organizations, including many small family foundations, she said.
Grant makers seem to hesitate to be a “first mover,” and often there isn’t buy-in from foundation leadership and boards, Sonenshine said. “I know a lot of program officers within donor groups who say that they want to do things differently and want to meet their partners where they are but they’re hamstrung by process or by precedent,” she said. “I think trying to change that takes time.”
Resistance often comes from philanthropy’s ingrained approach to funding, Marks said. Foundations are used to funding “this year’s expenses with this year’s revenue for this year’s program outcomes” rather than treating nonprofits as ongoing enterprises that need working capital, cash reserves, and infrastructure to grow, he said. There’s also a regulatory wrinkle: Because program-related investments, or PRIs, count toward a private foundation’s required 5 percent annual payout, some worry that such investments will eat into money they’d otherwise give away as grants, Marks said.
“They worry about cannibalizing their grants budget by making a PRI, as opposed to it being additive,” he said.
Where the Field Is Headed
For funders considering this path, the Bush Foundation’s Romano recommends learning from others in the field rather than starting from scratch. One resource he points to is Mission Investors Exchange, a national membership network that helps foundations learn how to do this kind of investing, often from each other. Regional groups like the Minnesota Council on Foundations offer similar support closer to home, he said.
That’s how Bush approached preferred-stock investing, a new approach for it, Bile, the foundation’s grant-making director said. Instead of developing its own approach in isolation, the foundation sought out peers that had already tried it and learned from them, she said.
The growth of Mission Investors Exchange itself is a sign of how much interest in this kind of funding has increased. The network started in 2005 with a handful of foundations. Two decades later, it has more than 300 active members, including major foundations like Ford, Gates, and Rockefeller. Its April conference drew more than 800 attendees, enough to fill a waitlist months in advance, said Matt Onek, MIE’s president and CEO.
“We are no longer talking about if impact investing works or how impact investing works but rather how we can all deploy a greater amount of assets toward impact,” he said. “This is exactly the moment to come together and put more capital to work.”